Market Report · Southern OntarioJuly 2026 Southern Ontario Real Estate Market Report: What's Really Happening Across the GTA And Surroundings📅 Published August 7, 2026📊 Based on July

Dated: March 3 2026
Views: 50
A macro-strategic analysis for families, buyers, sellers, and investors in Southern Ontario — GTA, Milton, Mississauga, Oakville, Burlington, and Toronto.
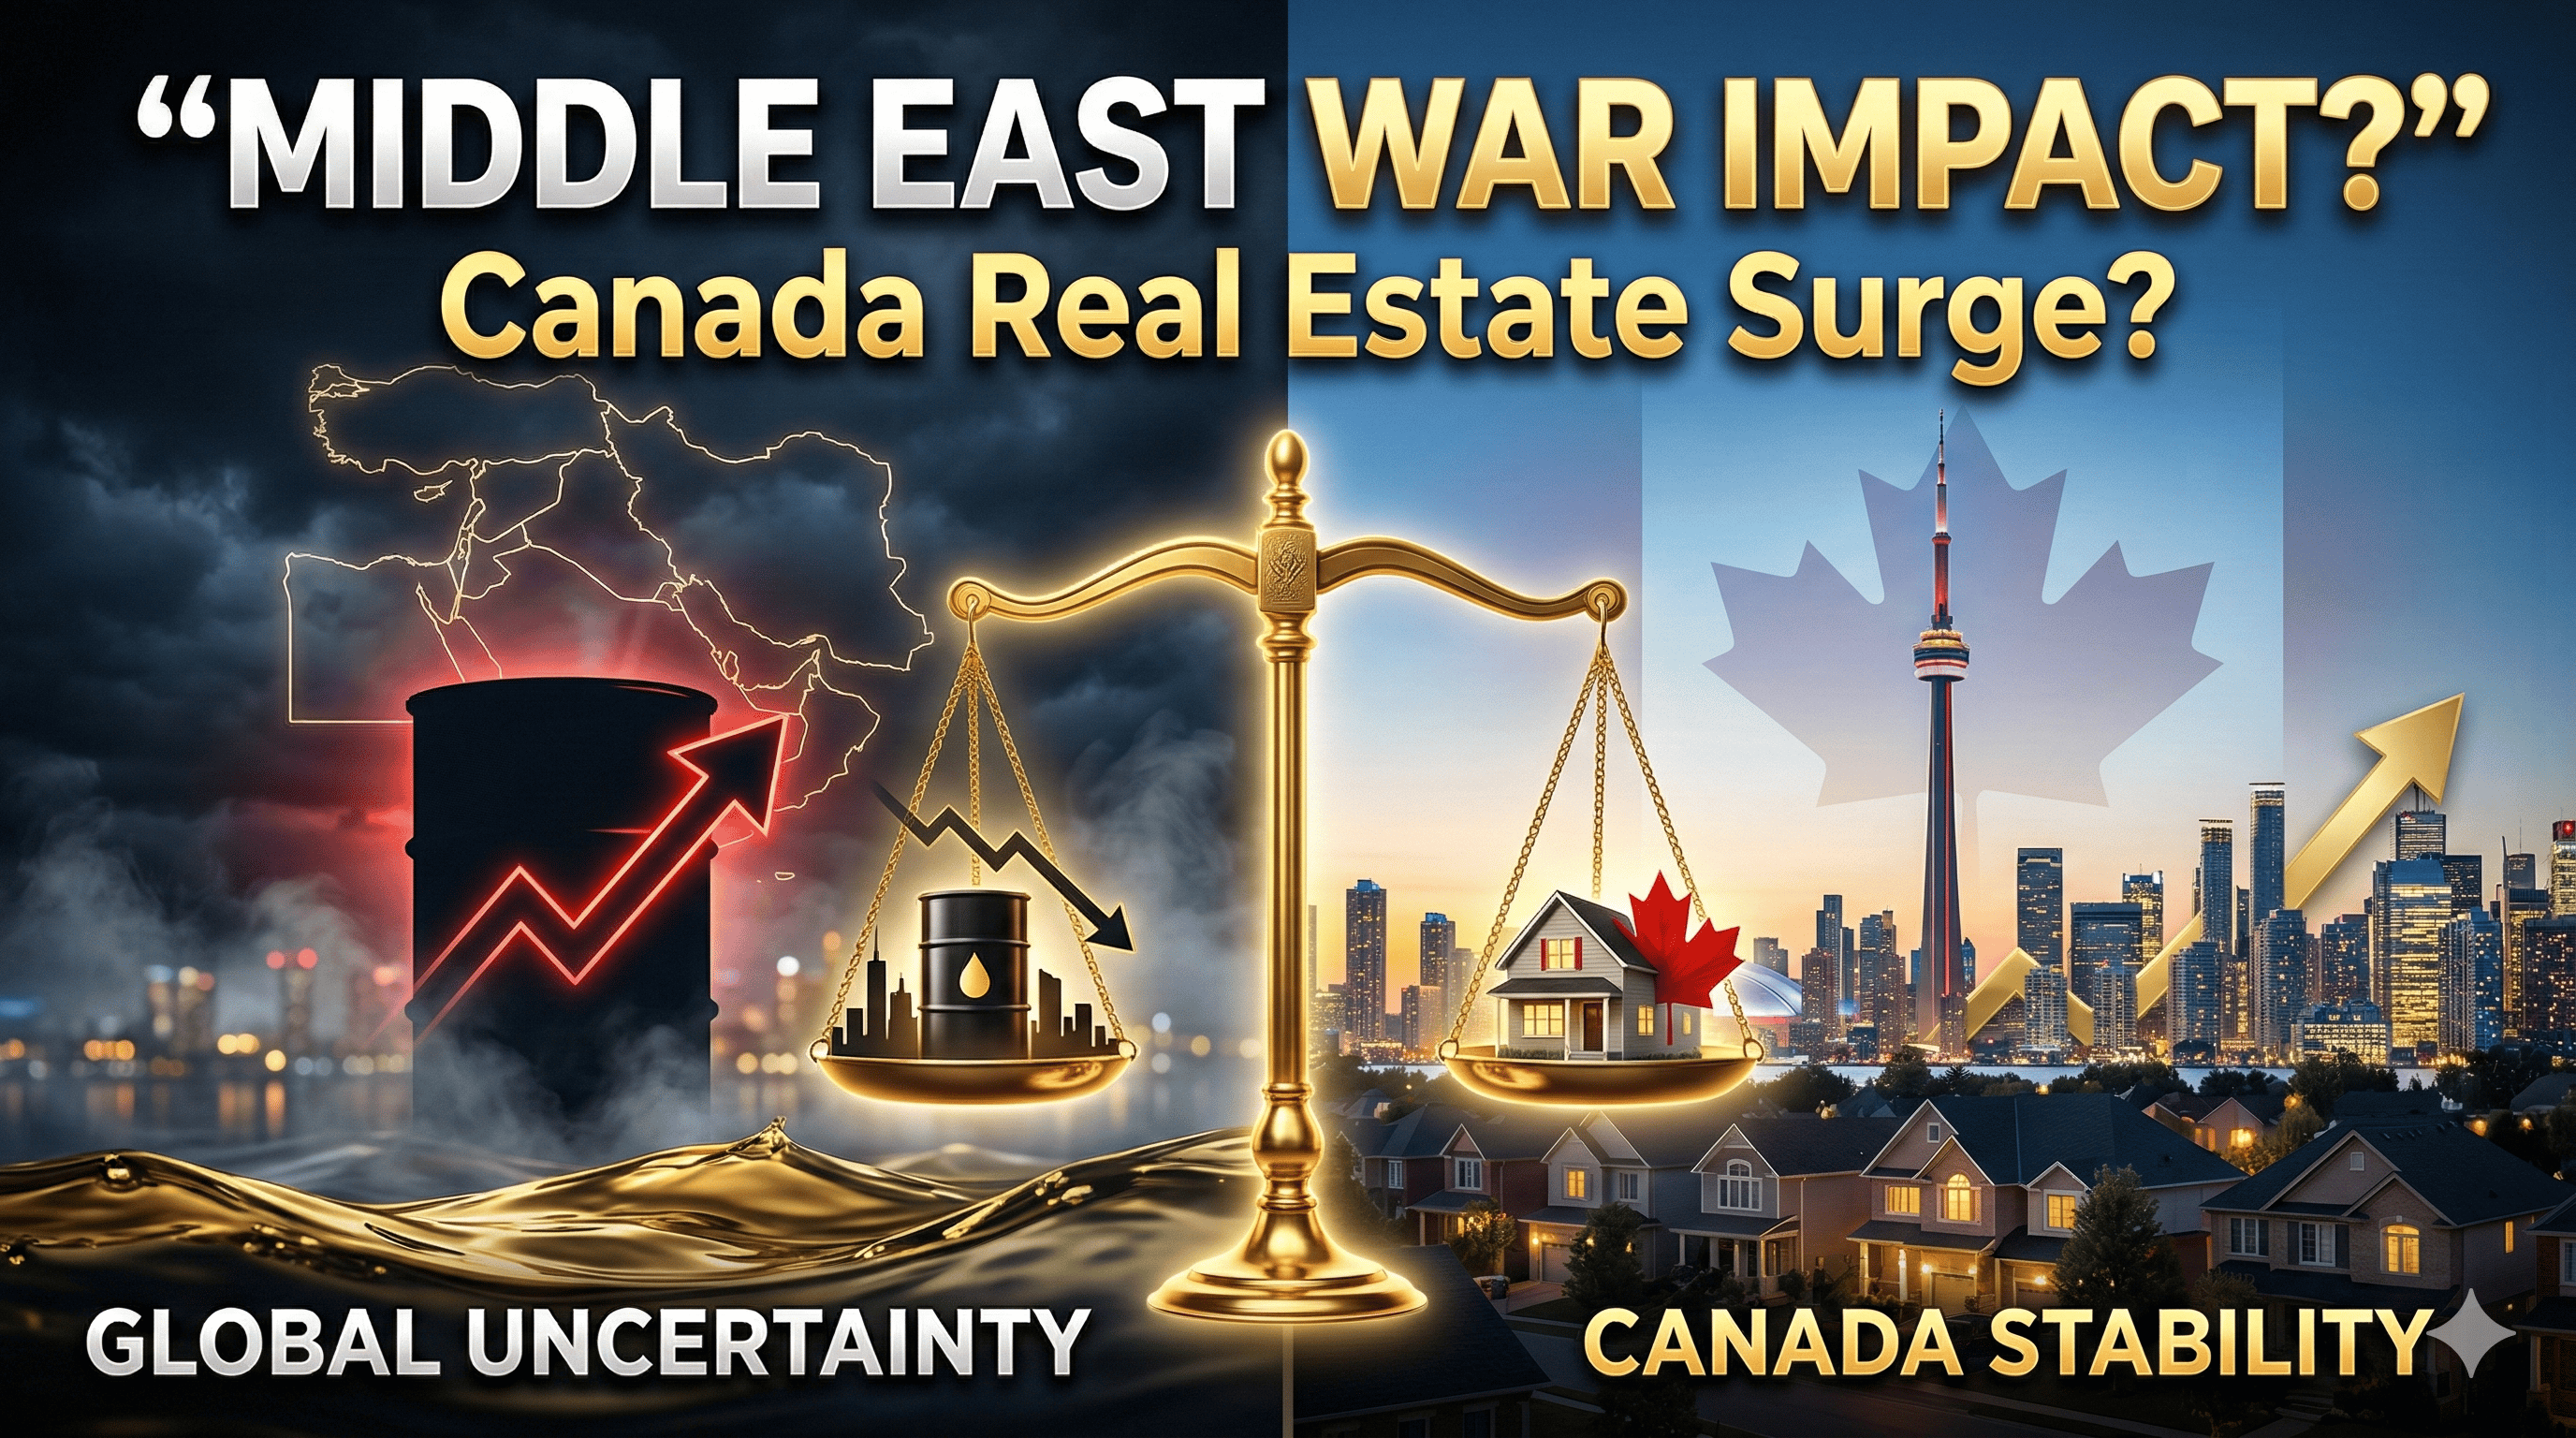
Global instability and Canadian stability: how geopolitical risk is reshaping real estate demand in Ontario for 2026. | Team Home Axe / Royal Canadian Realty, Brokerage
▶ Watch: Middle East War Impact & Canada Real Estate
Global tensions in the Middle East are raising energy prices, risk premiums, and uncertainty — but they are also reinforcing Canada's position as a stable, rules-based destination for both people and capital, with important implications for the Canada real estate outlook 2026 and the Ontario housing market forecast.
The core story here is not that conflict creates a real estate boom. The more precise and analytically sound argument is this:
"Periods of global instability often accelerate the rotation of families, professionals, and investors toward safer, rules-based jurisdictions — reshaping demand in markets like the GTA, Milton, Mississauga, Oakville, Burlington, and Toronto."
— Team Home Axe Research Desk, 2026This analysis draws on updated research from Reuters, Bloomberg, the Bank of Canada, CMHC, Statistics Canada, Global Affairs Canada, and IRCC. It is geopolitically neutral, data-driven, and designed to help clients in Southern Ontario make better-informed decisions — not headline-driven moves.
Current conflict involving multiple state actors across the Middle East has led to renewed volatility in global energy markets. Brent and WTI crude prices have risen sharply as traders price in the possibility of supply disruptions and the rerouting of tankers around constrained sea lanes — most critically, the Strait of Hormuz, through which approximately 20% of the world's seaborne oil supply passes.
This elevated risk premium on oil matters for Canada in several ways. Higher oil prices tend to lift headline inflation globally, complicating central bank paths for rate cuts and reinforcing a more cautious stance from policymakers. The Bank of Canada, currently holding its policy rate at 2.25% with inflation near its 2% target, must weigh these external shocks against a domestic economy that remains modest but positive.
In parallel, institutional and high-net-worth investors reassess their exposure to regions directly affected by geopolitical risk, often reallocating into assets and jurisdictions perceived as more predictable — from U.S. Treasuries to real estate in stable democracies. This "flight to quality" is not about taking sides; it is about risk management, diversification, and protecting family balance sheets in an uncertain world.
Canada enters 2026 as a G7 economy with an independent central bank, a transparent legal system, and a well-regulated mortgage and banking framework — all of which underpin its safe-haven perception among globally mobile families and institutional capital.
Institutions such as CMHC and Statistics Canada provide granular, transparent data on housing supply, demand, and demographics — reinforcing confidence for domestic and international investors alike. Canada's federal approach to foreign policy is widely characterized as multilateral and rules-based, with an emphasis on diplomacy, humanitarian support, and social cohesion at home.
For many globally mobile families, this combination of economic resilience, independent institutions, and social stability is precisely why Canada is viewed as a "safe haven" economy — not merely a commodity exporter, but a durable, livable destination for capital and people.
"In prior global shocks, Canada has absorbed inflows of people and capital due to its rule of law, institutional stability, and diversified economy."
This is the most important section of this analysis — and it deserves careful, respectful framing.
According to Global Affairs Canada, more than 85,000 Canadian citizens and permanent residents are currently registered across Middle Eastern countries on a voluntary basis — a figure that likely understates the true total, as registration is not mandatory.
Within that group, over 23,000 are registered in the United Arab Emirates, with additional communities in Lebanon, Saudi Arabia, Qatar, Israel, Iran, and other states across the region. These households benefit from consular advisories, evacuation planning, and support channels that Canada has a long history of activating in times of crisis.
Historically, Canada has adjusted immigration pathways, family reunification policies, and temporary measures during periods of instability or humanitarian need. In each episode, human mobility translated into real, local housing choices — returning Canadians moving back into the GTA, new permanent residents renting near transit in Mississauga or Toronto, or extended families consolidating around established communities in Milton, Oakville, and Burlington.
The reasons are practical, not speculative:
"Human mobility reshapes housing demand. When globally mobile households rebalance toward safer jurisdictions, the result is incremental, often high-quality demand for family-sized rentals, entry-level ownership, and investment properties."
Over the past decade, real estate in Gulf financial centres has been positioned as a strong asset class in its own right — supported by infrastructure investment, tax advantages, and global connectivity. None of that changes the fundamental value proposition of those markets.
What geopolitical risk does is prompt prudent investors to diversify their exposure — to allocate more capital to jurisdictions whose risk profile is less correlated with regional security dynamics. This is a standard portfolio management principle, not a judgment on any economy or region.
Large institutions may rebalance through public markets, while families and private investors may seek GTA real estate demand 2026 opportunities in established markets such as Toronto, Mississauga, Oakville, Burlington, and emerging growth corridors like Milton. The key analytical point is not that Gulf markets are "unsafe" — they are not — but that prudent investors typically prefer geographic diversification when regional risk rises.
Canada's housing market enters 2026 in a very different position from the frenzied period of 2020–2022. This context is critical — because a market that is stabilizing after a correction is far more responsive to incremental demand than one that is already overheated.
According to CMHC's Housing Market Outlook for 2026, home sales are projected to pick up but remain below historical averages, with prices seeing only modest gains after declining in 2025. In Ontario specifically, construction and home sales are expected to run below their 10-year averages, reflecting weaker demand, higher inventories, and more cautious builders.
RBC and other major bank economic research point to particularly elevated inventory and a buyer-friendly balance in Ontario — contributing to expectations of flat-to-slightly-negative price movement going into 2026 before gradual normalization. Local market data describes more months of inventory and a shift away from the "fear of missing out" mentality, especially for detached and higher-priced segments.
Higher oil prices from Middle East tensions feed through to inflation via fuel, transportation, and, indirectly, goods costs. The Bank of Canada does not respond to every short-term move — but it does monitor the persistence of inflationary pressures relative to its 2% target.
If the current oil spike proves short-lived and resolves within a few months, the impact on Canadian mortgage rates may be limited. The Bank of Canada could maintain its current 2.25% policy rate while monitoring growth, tariff risk, and inflation. Fixed mortgage rates would remain broadly stable.
If oil remains elevated for longer and pushes inflation higher, rate-cut expectations could be pushed out — keeping fixed-rate mortgages somewhat higher for longer than markets anticipated earlier in 2025. The key implication for borrowers: stress-test payments at slightly higher rate levels when planning your purchase horizon.
"In the medium term, if growth remains modest and inflation stays anchored near 2%, the path still points toward a more stable interest-rate environment for the Canada real estate outlook 2026 — even if the descent is slower than hoped."
— Bank of Canada Monetary Policy Framework, 2026The following table frames three simplified scenarios linking Middle East outcomes, oil prices, immigration flows, and the Ontario housing market forecast. These are decision-making frameworks, not predictions.
| Scenario | Conflict Duration | Oil Path (12–24 Months) | Immigration & Returning Canadians | Ontario Housing Impact (GTA, Milton, Mississauga, Oakville, Burlington) |
|---|---|---|---|---|
| 🟡 Scenario A Short Conflict | De-escalates within months; limited further spillover | Prices spike, then normalize toward pre-shock levels as supply routes adjust | Baseline immigration targets hold; modest uptick in returning Canadians within existing forecasts | Market continues to stabilize; buyers retain leverage with elevated inventory; GTA real estate demand 2026 improves gradually but remains measured. Rental markets in core Toronto and Mississauga tighten slowly. |
| 🔴 Scenario B Prolonged Conflict | Elevated tensions persist, with intermittent disruptions to shipping and energy infrastructure | Oil stays higher for longer, keeping inflation slightly above target and delaying rate cuts | Increased capital rotation and a more visible wave of returning Canadians and PRs from the Middle East — adding several thousand households beyond baseline to Ontario | Demand rotation absorbs excess inventory sooner in GTA and nearby markets; prices in Toronto, Milton, Oakville, Burlington, and Mississauga find a firm floor, with family-sized and transit-accessible properties leading any recovery. |
| 🟢 Scenario C De-escalation & Easing | Durable diplomatic de-escalation and gradual normalization in trade and energy shipping | Oil retraces significantly, easing inflation pressures and giving central banks more scope to cut rates over 2026–27 | Immigration recalibration remains in place but population inflows continue strong by historical standards, with fewer "shock-driven" returns | Lower mortgage rates revive domestic demand; Ontario's elevated but declining inventory supports a healthier, more balanced recovery. GTA real estate demand 2026 strengthens across all segments, especially in well-located markets. |
They can, indirectly. Higher oil prices may slow Bank of Canada rate cuts, while returning Canadians and global capital rotation can add incremental demand in markets like Ontario, particularly the GTA. The effect is more likely to manifest as a firm floor on prices and faster inventory absorption than as a sudden spike — especially under Scenario B (prolonged tensions).
More than 85,000 Canadians and permanent residents are registered across the region, including over 23,000 in the UAE, according to Global Affairs Canada. History shows that some households will choose to re-anchor in Canada when regional risks rise — even if only a small fraction do, it represents thousands of housing decisions concentrated in Southern Ontario.
Oil price spikes lift headline inflation, which can delay or reduce interest-rate cuts by the Bank of Canada. This keeps fixed mortgage rates higher for longer than would otherwise be the case. However, if the oil spike is short-lived, the mortgage rate impact may be minimal. Borrowers should stress-test their payments at slightly elevated rate assumptions as a precaution.
Yes, by most measures used by global investors and internationally mobile families. Canada's G7 status, independent central bank (Bank of Canada), strong rule-of-law institutions, transparent legal framework, and deep mortgage market all contribute to its safe-haven perception. This is regularly reflected in capital flows during periods of global uncertainty.
Official immigration targets are being recalibrated after several years of elevated inflows, but projections from Statistics Canada and IRCC still show strong inflows by historical standards. Ontario continues to receive the largest share of new permanent residents nationally — approximately 40–45% — supporting housing demand in the GTA, Mississauga, and surrounding communities.
With Ontario prices stabilizing after a meaningful correction, inventory elevated across most segments, and new construction starts declining, 2026 may represent a strategic entry window for qualified buyers who plan to hold long term. The case for waiting rests on hoping for further price declines — which are possible under Scenario C, but less likely if demand from returning Canadians and capital rotation materializes. The case for acting is access to selection, negotiating leverage, and a long runway of population-driven appreciation.
Core GTA markets — Toronto, Mississauga, Oakville, Burlington — and growth hubs like Milton, Ontario combine employment access, transit connectivity, and established communities that attract both newcomers and returning Canadians. Milton in particular offers family-friendly infrastructure with GO Transit access and a rapidly growing professional community, making it well-positioned to capture demand from globally mobile households.
Geopolitical events influence energy prices, interest rates, risk appetite, migration flows, and capital allocation — all of which shape local housing demand and supply over multi-year horizons. The transmission is rarely immediate or linear; it operates through multiple channels simultaneously. The most durable effects tend to come from shifts in human mobility and long-term capital reallocation, not from short-term market sentiment alone.
This analysis draws on research and data from: Reuters, Bloomberg, The Guardian, Bank of Canada Monetary Policy Reports, CMHC Housing Market Outlook 2026, Statistics Canada, Global Affairs Canada, CTV News, Global News, TD Economics, RBC Economics, Dallas Federal Reserve, Government of Ontario Long-Term Economic Report, and IRCC immigration data. All geopolitical and economic data cited reflects publicly available reporting as of March 2026.
"Sharp Moves. Smart Homes."
For families, sellers, and investors navigating the impact of global uncertainty on Canadian housing, Team Home Axe at Royal Canadian Realty Brokerage connects macro insight with on-the-ground expertise in the GTA, Milton, Mississauga, Oakville, Burlington, and wider Ontario.
Disclaimer: This blog is for informational and educational purposes only. It does not constitute legal, financial, mortgage, or investment advice. All data, statistics, and projections referenced are drawn from publicly available third-party sources including Government of Canada agencies, major Canadian financial institutions, and international news organizations. Readers are encouraged to consult qualified professionals before making any real estate, financial, or legal decisions. Team Home Axe and Royal Canadian Realty, Brokerage are not responsible for actions taken based on this content. Market conditions may change. Always do your own due diligence.
Monthly AwardsDiamond Club: May 2025Gold Club: August 2025, April 2025....
📊 Market Report · May 2026April 2026 Southern Ontario Real Estate Market Report: What's Really Happening Across the GTA, Milton, Oakville, Mississauga, Waterloo & Hamilton
Team Home Axe | Royal Canadian Realty, Brokerage Sharp Moves · Smart HomesMilton Real Estate GuideBest Neighborhoods in Milton for Families, Commuters & First-Time BuyersBy
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 10:41 AM UTC
Show More...
 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned
by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
REALTOR® contact information provided to facilitate inquiries from consumers interested in Real Estate services. Please do not contact the website owner with unsolicited commercial offers.
Show More...
