Market Report · Southern OntarioJuly 2026 Southern Ontario Real Estate Market Report: What's Really Happening Across the GTA And Surroundings📅 Published August 7, 2026📊 Based on July

Dated: March 13 2026
Views: 34
Bill C-4 received Royal Assent on March 12, 2026. Here's what the Making Life More Affordable for Canadians Act means for household purchasing power — and what it signals for housing demand across Toronto, Mississauga, Milton, Oakville, and Burlington.
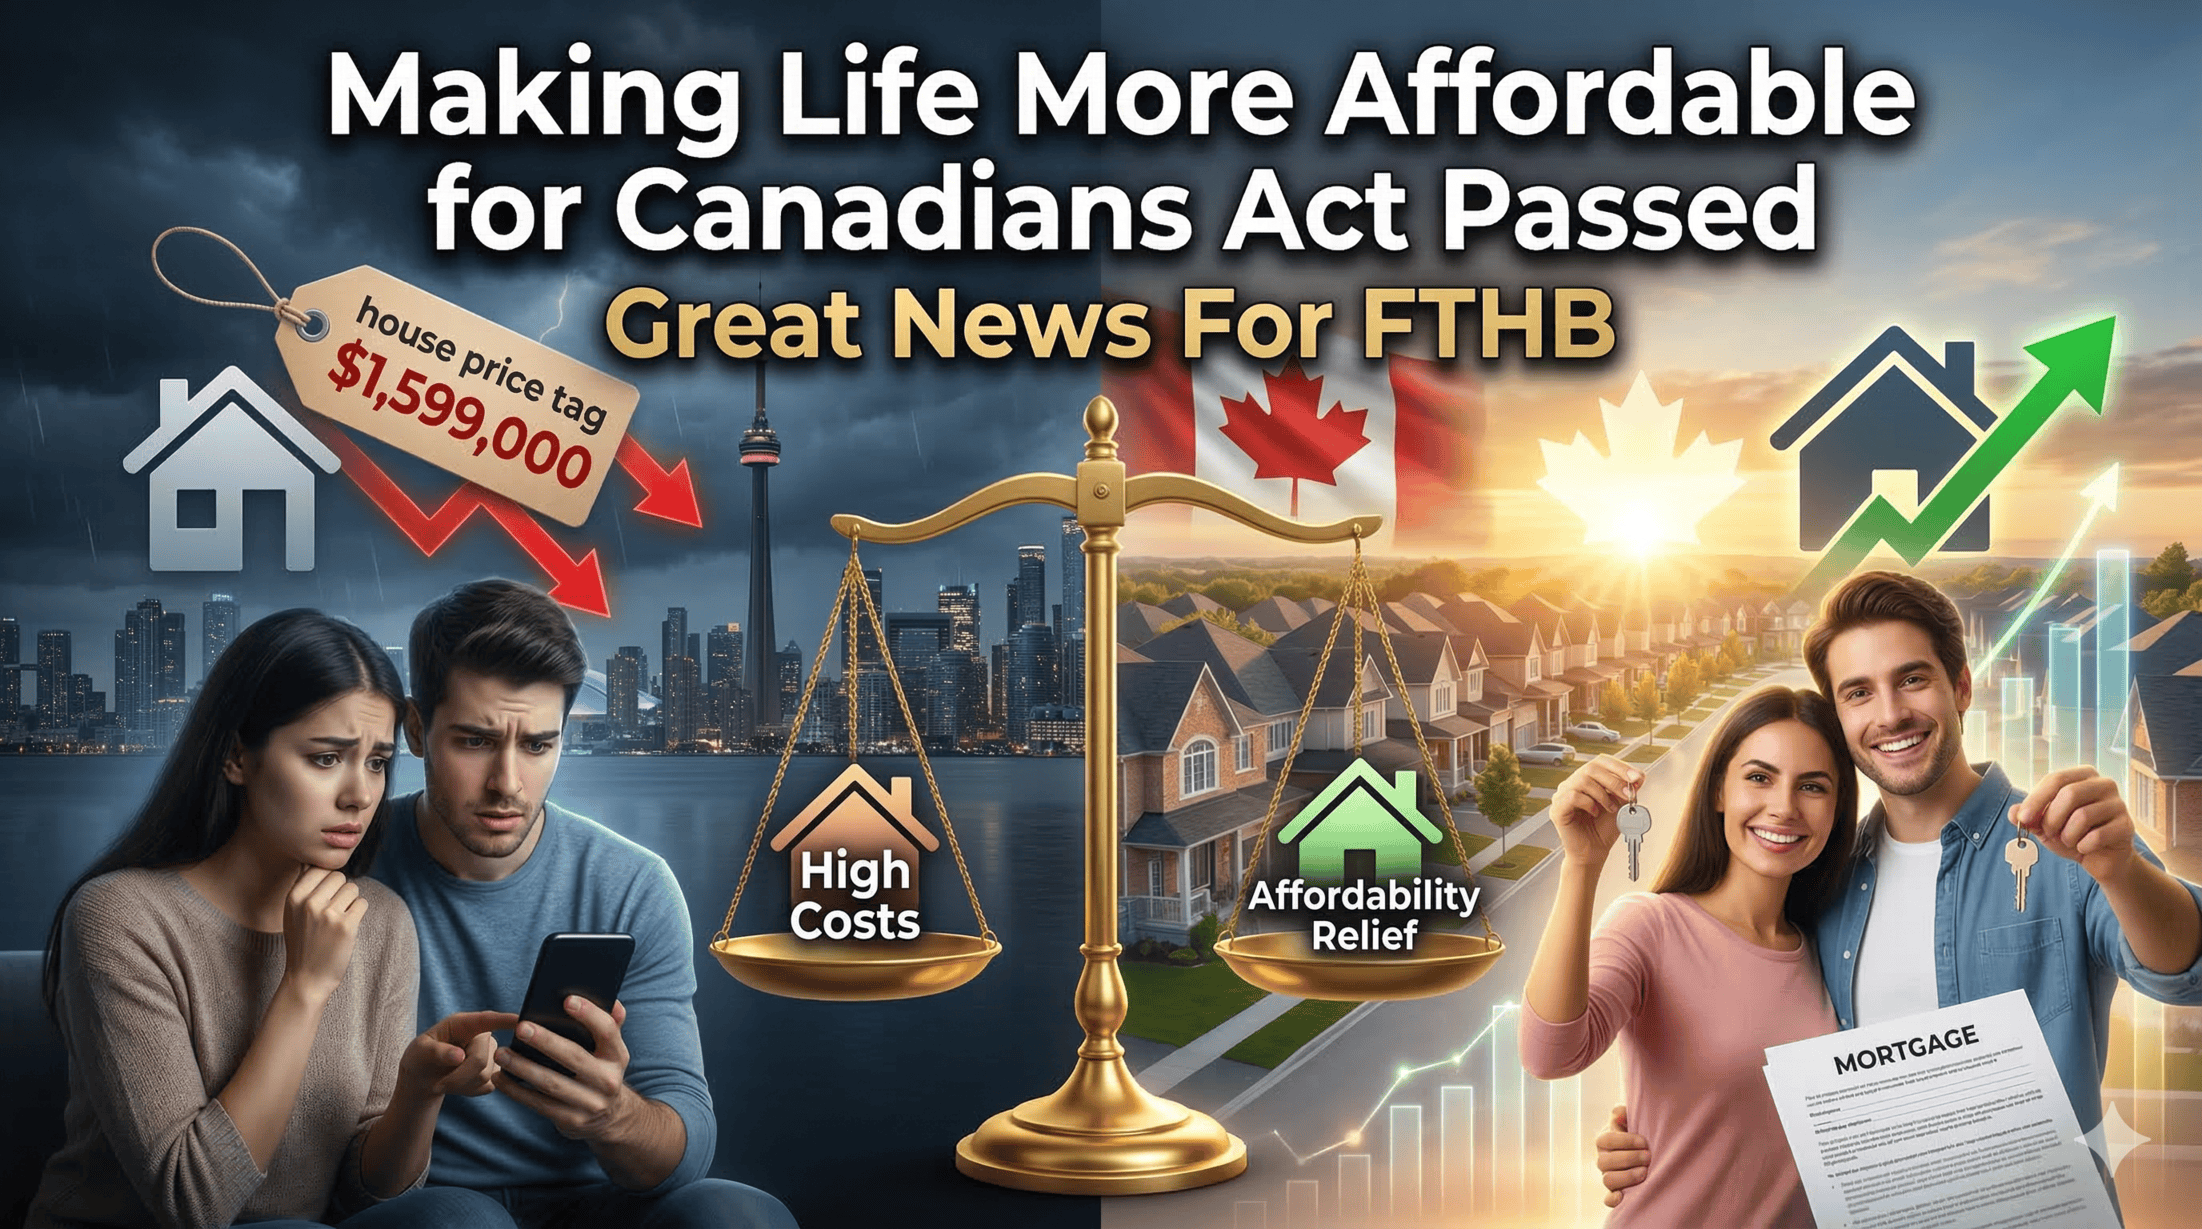
Canada's first-time home buyer GST relief and affordability measures signal improving conditions for the GTA housing market. | Team Home Axe · Royal Canadian Realty Brokerage
On March 12, 2026, Bill C-4 — the Making Life More Affordable for Canadians Act — received Royal Assent, enacting three targeted measures: a middle-class income tax cut, a GST rebate for first-time buyers of new homes, and the permanent removal of the federal consumer fuel charge.
The government's stated goal is straightforward: lower everyday costs, raise disposable income, and support a stronger economy for households squeezed by high housing costs and past inflation. The legislation complements other recently enacted measures including the Canada Groceries and Essentials Benefit — up to $1,890 in 2026 for a family of four — and the expansion of the Automatic Federal Benefits program.
"Canada's new affordability legislation will modestly lift household purchasing power and confidence, with meaningful — but not explosive — implications for the GTA housing market over the next 12–24 months."
Policy moves like this affect the Canada housing market in 2026 by altering after-tax income, transportation costs, and consumer sentiment — which in turn shapes how quickly sidelined buyers re-enter the market. In the Greater Toronto Area, where affordability remains stretched and inventory has risen, these measures are more likely to stabilize demand and support a gradual recovery than to trigger another speculative boom.
Bill C-4 has three core measures:
The first marginal personal income tax rate drops from 15% to 14%, benefiting nearly 22 million Canadians. Relief of up to $420 per person or $840 for a two-income family, focused on incomes under $117,045.
Federal GST eliminated on new homes up to $1 million for first-time buyers. Reduced GST on homes between $1M–$1.5M. Applies to agreements signed March 20, 2025 to 2031.
The consumer carbon price is permanently removed from federal legislation, lowering gasoline prices in most provinces by up to 18 cents per litre versus 2024–2025 levels.
Federal affordability initiatives affect housing through several interconnected channels. Understanding these mechanisms helps buyers, sellers, and investors interpret policy signals correctly.
Tax cuts and transfers raise after-tax income, improving debt-service capacity at a time when the Bank of Canada projects only moderate income growth and persistent affordability challenges in major centres like Toronto.
Direct, visible relief — fuel savings, grocery benefits, tax refunds — can improve sentiment, encouraging households who delayed moves during 2025's slowdown to revisit purchase decisions. Confidence is a powerful leading indicator in housing markets.
With the Bank of Canada policy rate at 2.25% and mortgage rates stabilizing, the Bank of Canada expects residential investment to grow moderately as pent-up demand returns — even as affordability remains strained in high-price markets.
Lower transportation and commuting costs generally support suburban and exurban living. Statistics Canada data shows that Toronto's population growth has recently flattened after a period of very rapid expansion and significant out-migration within Ontario — a structural trend that affordability measures may deepen.
For the GTA housing market — including Toronto, Mississauga, Milton, Oakville, and Burlington — the new affordability framework interacts with an already cooled environment of higher inventory, softer prices, and cautious buyers.
| Market | Key Demand Driver | Price Tone | Notes |
|---|---|---|---|
| Toronto | Pent-up demand, immigration, improved incomes | Soft to flat | High inventory; uneven recovery across condo vs. low-rise |
| Mississauga | Trade-off between price and proximity to jobs | Soft but stabilizing | Appeals to move-up buyers seeking more space than downtown |
| Milton | Relative affordability, family-oriented product | More resilient | Beneficiary of westward migration and improved transport links |
| Oakville | Higher-income households, lifestyle focus | Soft, segmented | Luxury and move-up segments more sensitive to rates |
| Burlington | Mature suburban market, good connectivity | Stable to mildly soft | Draw for downsizers and families looking westward |
Western GTA communities — Milton, Mississauga, Oakville, and Burlington — are structurally positioned to capture demand uplift from affordability policies. Here's why:
"The Milton Ontario real estate market, Mississauga housing market, Oakville real estate market, and Burlington housing market are likely to see relatively stronger activity once buyers regain confidence."
Understanding current market dynamics is essential for contextualizing the Canada affordability policy housing impact.
CMHC's Spring 2026 Housing Supply Report notes that housing starts rose 6% in 2025, driven by record rental and "missing middle" construction — while ground-oriented construction weakened in Toronto and unsold condo inventory increased. This supply dynamic creates a nuanced environment: choice in some segments, constrained availability in others.
The Bank of Canada projects stable policy rates in the near term, with mortgage rates roughly steady in early 2026 and likely to drift modestly higher from mid-2026 as policy normalizes. This creates a narrow but real window of opportunity for buyers with financing pre-arranged.
CMHC and private-sector research indicate that home prices fell approximately 2% nationally in 2025, with larger declines in Ontario, and that buyers and developers have adopted a wait-and-see stance amid economic uncertainty. Ontario is expected to be the only province where prices continue to decline modestly in 2026, before recovering in 2027.
Improved after-tax income, targeted GST relief for first-time purchasers of new homes, and lower transportation costs support purchasing confidence without eliminating the need for careful budgeting. With prices under pressure and inventory elevated in parts of the GTA, qualified buyers may find a rare combination of improved affordability and choice — especially in western GTA suburbs.
Policy changes should help market liquidity by bringing more end-users back into the market — but national and Ontario-specific forecasts suggest sellers should not assume rapid price appreciation in 2026. Realistic pricing, strong presentation, and flexible terms will remain important to convert increased interest into firm offers.
CMHC expects Ontario's prices to bottom in 2026 with recovery into 2027, and the Bank of Canada anticipates moderate growth in residential investment driven by pent-up demand. For long-term investors focused on the GTA, this suggests entry pricing may be more attractive — but income properties must be underwritten conservatively given rising rental supply and slower rent growth.
This analysis does not constitute financial or investment advice. All market forecasts cited are from third-party institutional sources.
Policy and macro shifts — from Bill C-4 to Bank of Canada decisions to CMHC forecasts — increasingly shape where and how Canadians buy, sell, or invest in housing. Interpreting these signals at the local level requires both data and on-the-ground insight.
Team Home Axe at Royal Canadian Realty Brokerage monitors economic policy, central-bank communications, and housing-market research to help clients translate big-picture developments into practical decisions.
Monthly AwardsDiamond Club: May 2025Gold Club: August 2025, April 2025....
📊 Market Report · May 2026April 2026 Southern Ontario Real Estate Market Report: What's Really Happening Across the GTA, Milton, Oakville, Mississauga, Waterloo & Hamilton
Team Home Axe | Royal Canadian Realty, Brokerage Sharp Moves · Smart HomesMilton Real Estate GuideBest Neighborhoods in Milton for Families, Commuters & First-Time BuyersBy
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 10:41 AM UTC
Show More...
 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned
by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
REALTOR® contact information provided to facilitate inquiries from consumers interested in Real Estate services. Please do not contact the website owner with unsolicited commercial offers.
Show More...
